Portugal’s commercial property market gathers momentum as international capital flows in
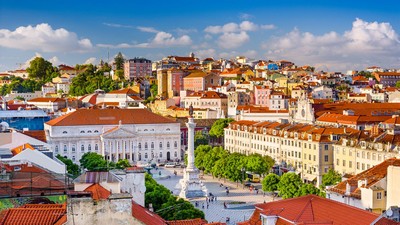
Lisbon: Portugal’s commercial property market is entering the final months of 2026 with renewed momentum, as international investors continue to commit capital, domestic buyers strengthen their presence and demand remains particularly robust for hotels, retail properties and logistics assets.
After a period of adjustment amid challenging global economic conditions, the Portuguese commercial real estate sector has shown clear signs of recovery during the first nine months of the year. Investors are demonstrating growing confidence in the market, with hospitality and retail emerging as the dominant destinations for capital, while alternative sectors including data centres, senior living and other specialised assets are increasingly attracting institutional attention.
Although comprehensive figures for the third quarter have yet to be published by the major international property consultancies, investment data covering the first six months of 2026 already indicate a substantial level of activity, with commercial property transactions reaching approximately €1.4 billion.
Estimates from leading consultancies show a broadly consistent picture. Savills recorded around €1.40 billion in commercial real estate transactions during the first half of the year, representing a 14 per cent increase compared with the same period in 2025. JLL placed the corresponding figure at approximately €1.42 billion, up 11 per cent year-on-year, while Cushman & Wakefield estimated total investment at €1.375 billion, reflecting growth of about 13 per cent.
The modest differences between the figures are largely attributable to variations in the transactions and property categories included in each consultancy’s calculations. Nevertheless, the overall direction is unmistakable: Portugal remains an attractive destination for commercial property investment, even as investors worldwide contend with higher financing costs, geopolitical uncertainty and uneven economic growth.
The market’s performance was particularly impressive during the opening three months of 2026. Savills recorded approximately €914 million in commercial property transactions during the first quarter, while JLL estimated activity at around €930 million.
The pace of transactions subsequently moderated during the second quarter, but the slowdown did not signal a loss of investor confidence. Rather, it reflected the normalisation of an exceptionally strong opening period and the more selective approach being adopted by investors in an increasingly competitive market.
Investors have remained focused on assets capable of generating relatively stable income and benefiting from long-term structural trends. This has placed hotels, retail properties and logistics facilities at the centre of the market, while traditional office investment has remained comparatively restrained.
The hospitality sector has been one of the strongest performers of 2026, benefiting from Portugal’s continuing appeal as an international tourism destination and from sustained demand for accommodation in the country’s major cities and resort areas.
Savills recorded approximately €508 million of investment in hotels during the first half of the year. The figure accounted for around 36 per cent of total commercial property investment and represented a striking 54 per cent increase from the same period a year earlier.
One of the most significant transactions involved the acquisition of a 72 per cent stake in the Corinthia Lisbon Hotel for approximately €150 million. The transaction underlined the continued appetite for high-quality hospitality assets in established Portuguese locations.
JLL’s assessment similarly highlighted hospitality as one of the principal engines of the market, estimating that hotels and related hospitality assets accounted for roughly 34 per cent of commercial property investment during the first half of 2026.
The strength of the hotel market reflects broader confidence in Portugal’s tourism economy. International visitors, established tourism infrastructure and the country’s reputation as a European leisure and business destination continue to support demand for well-positioned hotel properties.
Retail was another major pillar of Portugal’s commercial property market during the first half of the year.
Savills recorded approximately €464 million in retail transactions, equivalent to around 33 per cent of total commercial property investment. The scale of activity demonstrates that investors continue to see value in established shopping destinations despite the profound changes taking place in the wider retail industry.
Well-located shopping centres and other prime retail properties remain particularly attractive because of their established customer bases, strong transport connections and potential for stable rental income.
The performance of retail also suggests that investors are increasingly distinguishing between different segments of the sector rather than treating physical retail as a single category. Prime assets with strong occupancy, established tenants and sustainable footfall are continuing to command attention.
Industrial and logistics properties also continued to attract investment, although volumes were significantly lower than those recorded in hospitality and retail.
Approximately €164 million was invested in the sector during the first half of 2026, according to Savills. The continued interest reflects the longer-term transformation of Portugal’s economy and the growing importance of logistics infrastructure linked to e-commerce, manufacturing, distribution and international trade.
Strategically located logistics facilities are increasingly viewed as essential infrastructure rather than simply conventional commercial property. Investors are therefore paying close attention to properties capable of serving major population centres, transport corridors and industrial clusters.
By contrast, office investment remained relatively subdued. Savills recorded only around €68 million in office transactions during the first half of the year.
The comparatively weak performance reflects the structural changes affecting office markets across Europe. The widespread adoption of hybrid and flexible working arrangements has made investors more cautious, particularly when considering older buildings that require substantial investment to meet modern environmental, technological and workplace standards.
Prime office properties, however, continue to attract interest where they offer strong locations, high-quality facilities and reliable tenants. The market is increasingly divided between premium assets capable of meeting changing occupier requirements and older buildings facing greater pressure to reposition or undergo extensive refurbishment.
Portugal’s commercial property market continues to benefit significantly from international capital.
Savills estimated that approximately 61 per cent of commercial property investment during the first half of 2026 originated from outside Portugal. Major sources of capital included France, Britain, the United States, Spain and Switzerland.
JLL’s figures pointed to an even stronger international presence, estimating that foreign investors accounted for approximately 65 per cent of first-half investment.
The figures nevertheless reveal an important development: Portuguese investors themselves are becoming increasingly active. Domestic capital accounted for an estimated 35 per cent of investment according to JLL, highlighting the growing role of local institutions and private investors in the market.
The combination of international and domestic capital is helping to broaden the market and reduce its dependence on any single category of investor.
One of the most notable features of the Portuguese property market in 2026 has been the growing diversification of investor interest.
While hotels, shopping centres, logistics facilities and prime offices remain established investment categories, investors are increasingly looking beyond traditional commercial property.
Data centres are emerging as an important standalone asset class, driven by the rapid expansion of digital infrastructure, cloud computing and artificial intelligence. The growing demand for computing capacity is creating new requirements for specialised facilities capable of supporting large-scale digital operations.
Senior residences and other living-related assets are also attracting greater institutional interest. Demographic change, evolving consumer preferences and the growing professionalisation of specialised living facilities are encouraging investors to examine the sector as a long-term source of relatively resilient demand.
This expansion into alternative assets represents a broader transformation in the Portuguese investment landscape. Institutional investors are increasingly seeking opportunities linked to structural economic and demographic trends rather than relying exclusively on conventional offices, hotels and retail properties.
Despite changes in interest rates and financing conditions, prime yields have remained relatively stable across major commercial property categories.
Cushman & Wakefield reported prime yields of around 5 per cent for offices, 5.5 per cent for logistics assets and approximately 6.15 per cent for shopping centres at the end of the second quarter.
The relative stability of yields suggests that investors continue to regard high-quality Portuguese commercial property as a long-term asset, even though they remain selective about pricing and financing.
Prime assets are benefiting from limited availability, while strong occupier demand in several sectors is helping to underpin valuations. This is particularly significant at a time when investors in many European markets are reassessing property values in response to changes in borrowing costs and economic expectations.
As Portugal’s commercial property market moves towards the final quarter of 2026, the outlook remains broadly positive.
The market is being supported by a combination of factors, including continued international investor interest, growing participation by Portuguese capital, limited availability of prime assets and resilient demand from occupiers.
The strong performance of hospitality and retail is expected to remain an important feature of the market, while logistics, data centres and senior living could play an increasingly prominent role in the next phase of growth.
At the same time, investors are likely to remain highly selective. Rising operational costs, financing conditions, sustainability requirements and changing patterns of consumer and workplace behaviour mean that not every property will benefit equally from the recovery.
The distinction between prime and secondary assets is therefore expected to become increasingly important. Properties in strong locations, with modern facilities, reliable tenants and clear long-term income potential, are likely to remain the preferred targets for investors.
For Portugal, the continued flow of international capital is particularly significant. It reflects confidence not only in individual properties but also in the country’s broader economic position, tourism sector, infrastructure and role within the European market.
With investment activity continuing and several alternative property sectors gaining momentum, Portugal’s commercial real estate market appears to be closing 2026 on a considerably stronger footing than it began the year. If current trends persist, the country is likely to remain firmly on the radar of international and domestic investors as they look for opportunities in Europe’s increasingly competitive property landscape.