France rejects ECB intervention as borrowing costs rise amid budget uncertainty
Paris: France’s economic situation was becoming increasingly difficult as borrowing costs rose and investors focused on the country’s strained public finances, but the head of the Bank of France said Paris did not, at that stage, need intervention from the European Central Bank.
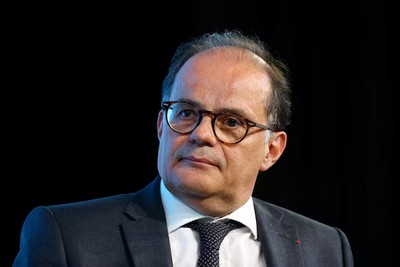
Bank of France Governor Emmanuel Moulin said the rise in French borrowing costs was closely linked to the country’s comparatively high budget deficit and continued political uncertainty surrounding the government’s efforts to secure parliamentary approval for its 2027 budget.
Moulin said the most immediate solution lay within France itself rather than at the headquarters of the European Central Bank in Frankfurt.
“Today, there is no need to seek the solution in Frankfurt; the solution is here at home,” Moulin said in an interview with France Inter radio.
His remarks came as French government borrowing costs rose amid a broader global bond-market selloff, with investors increasingly scrutinizing the fiscal positions of major economies.
France had faced particular attention because of the combination of a large budget deficit, elevated borrowing requirements and political uncertainty over the government’s ability to push its deficit-reduction plans through parliament.
Moulin said the gap between French borrowing rates and those of other eurozone countries was linked to France’s deficit, which remained higher than that of several other member states, as well as uncertainty over the budget vote.
He argued that securing parliamentary approval for a deficit-cutting budget was essential to improving market confidence.
The French government, led by Prime Minister Sebastien Lecornu, had set a target of reducing the budget deficit from 5.4 percent of economic output in 2026 to 5 percent in 2027.
That target placed the government under considerable pressure as it attempted to navigate a deeply divided parliament and opposition from both the political right and left.
The political stakes were heightened by France’s approaching presidential election in 2027. Lecornu’s government was therefore confronting not only the technical challenge of reducing the deficit but also intense political opposition to measures that could involve spending restraint, higher revenues or other unpopular fiscal choices.
France had presented its 2027 budget bill on October 1, beginning a parliamentary process that was expected to test the government’s ability to maintain support for its fiscal strategy.
The country had already experienced two government collapses over budget disputes, in 2024 and 2025, underscoring the political sensitivity surrounding fiscal policy.
Against this backdrop, the rise in borrowing costs had become an additional concern.
Higher government borrowing costs could increase the expense of servicing France’s substantial public debt, potentially making deficit reduction more difficult and narrowing the government’s room for maneuver.
Moulin nevertheless rejected the idea that the European Central Bank should intervene immediately to ease French borrowing costs.
“I do not think that the European Central Bank needs to intervene as of now, given the current conditions,” he said.
His comments came after far-right leader Marine Le Pen called for discussions with the ECB over possible action to reduce France’s borrowing costs.
Asked about the proposal, Moulin said such intervention was not part of the ECB’s role under the circumstances.
The debate highlighted the tension between national fiscal policy and the wider monetary framework of the eurozone.
While the ECB has tools for addressing financial-market stress and maintaining monetary stability, the Bank of France governor’s position was that France’s immediate challenge was fundamentally domestic: reducing its deficit, securing parliamentary backing for the budget and restoring greater certainty around the country’s fiscal direction.
The government’s deficit target for 2027 was therefore emerging as a central test of its economic strategy.
Reducing the deficit from 5.4 percent to 5 percent of GDP would require the government to implement significant fiscal measures at a time when political parties across the spectrum were challenging aspects of its budget plans.
The situation also carried implications beyond France. As one of the eurozone’s largest economies, developments in French government bond markets could attract wider investor attention, particularly if concerns about public finances translated into persistently higher borrowing costs.
For Paris, however, the immediate task remained domestic.
Moulin’s assessment suggested that France could not rely on monetary intervention to compensate for political uncertainty or fiscal weakness. The government’s ability to pass its budget and demonstrate a credible path toward deficit reduction remained central to efforts to ease pressure on its borrowing costs.
The episode also illustrated the broader fiscal challenges confronting the eurozone, where governments were attempting to reduce deficits while coping with higher financing costs, political fragmentation and continued economic uncertainty.
France’s experience, alongside Italy’s call for greater flexibility over EU fiscal rules, underscored the competing pressures facing European policymakers: governments were being urged to maintain fiscal discipline while also seeking sufficient room to respond to difficult economic conditions.
For France, the message from its central bank was clear: the immediate response to rising borrowing costs was expected to come through national fiscal policy rather than emergency action from the ECB.